Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
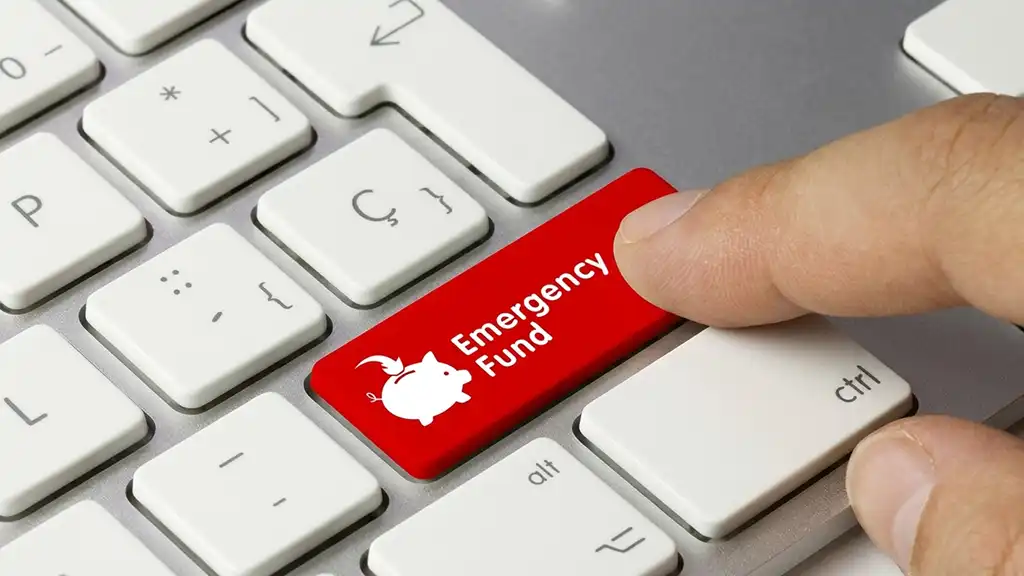
An emergency fund is one of the most important parts of a healthy financial plan. Unexpected expenses, medical bills, urgent car repairs, or a sudden loss of income can create financial pressure when you are least prepared. Having money set aside for these situations can help you manage difficult moments without relying on credit cards or personal loans.
However, saving money is only part of the process. Choosing the right account to hold your emergency fund is equally important. Ideally, your savings should remain safe, earn competitive interest, and be accessible whenever an unexpected expense arises.
A high annual percentage yield (APY) can help your balance grow, but interest should not be the only factor guiding your decision. Monthly fees, withdrawal options, transfer times, minimum balance requirements, and account restrictions can all affect how useful an account will be during an emergency.
For most people, an FDIC-insured high-yield savings account provides a practical combination of security, liquidity, and interest earnings. Several online banks offer these accounts with relatively simple terms, making them suitable for people who want to build their financial safety net.
What Should You Look for in an Emergency Savings Account?
Before opening an account, consider the features that matter most for emergency savings.
Federal deposit insurance: Eligible deposits at FDIC-insured banks are generally protected up to $250,000 per depositor, per insured bank, for each ownership category.
Competitive interest: A strong APY allows your savings to earn interest without exposing the money to investment-market fluctuations.
Low or no fees: Monthly maintenance charges can gradually reduce your emergency reserve.
Easy access: You should be able to withdraw money or transfer it to your checking account without unnecessary complications.
Simple requirements: Avoid accounts with complicated deposit conditions or balance rules unless you can comfortably meet them.
Your emergency fund should support your financial stability, not create additional banking responsibilities.
1. Marcus Online Savings Account
Marcus by Goldman Sachs is worth considering for savers who prefer a straightforward online savings account. Its general appeal comes from uncomplicated account requirements and a focus on helping customers earn interest on money they do not need for everyday spending.
The account has traditionally offered no minimum deposit requirement to open and no monthly maintenance fee. These features can make it accessible to people who are building an emergency fund gradually rather than depositing a large amount immediately.
Another consideration is how quickly you can transfer money when necessary. Marcus offers electronic transfer options, although processing times depend on the transaction and applicable cutoff times.
This account may suit someone who wants to keep emergency savings separate from their regular checking account without managing multiple banking products.
Before applying, check the current APY, transfer limits, and withdrawal arrangements because rates and account terms can change.
2. Ally Bank Savings Account
Ally Bank is another option for people who value convenience and savings-management tools. Its online savings account has generally offered no monthly maintenance fee and no minimum opening deposit.
One useful feature is the ability to organize savings into digital buckets. These categories allow customers to divide their balance according to different goals without necessarily opening separate accounts for every purpose.
For example, you could organize your savings around medical expenses, home repairs, vehicle problems, and temporary income loss. Although the money remains part of your overall savings balance, these categories can make your progress easier to understand.
Ally can be particularly helpful for people who are still developing consistent saving habits. Organizing money by purpose may reduce the temptation to use emergency savings for nonessential purchases.
The main consideration is accessibility. Review transfer timing and withdrawal options before deciding how much of your emergency reserve to keep in this account.
3. EverBank Performance Savings
EverBank Performance Savings is another account to compare when looking for a competitive savings rate. Its online structure can appeal to customers who want to earn interest without maintaining a complicated collection of banking products.
The account has historically offered competitive variable APYs and has generally not required a minimum opening deposit. However, current terms should always be confirmed directly with the bank.
One advantage of a savings account with straightforward requirements is that you can focus on building your reserve instead of tracking qualifying activities every month.
For emergency savings, this simplicity matters. You may already have enough financial responsibilities to manage without worrying about whether a particular deposit or transaction qualifies you for a promotional rate.
EverBank may be suitable for savers who are comfortable banking online and want to compare its current yield against other fee-free savings accounts.
As with any variable-rate account, remember that the advertised APY can change over time.
4. Discover Online Savings Account
Discover’s online savings account is another option for people who want a relatively simple place to hold emergency cash. The account has traditionally offered no monthly maintenance fee and no minimum balance requirement to open it.
These features can make it attractive to new savers who want to begin with small, regular deposits.
A major advantage of a straightforward savings account is predictability. You can establish a regular contribution schedule, monitor your balance, and earn interest without needing to satisfy numerous linked-account conditions.
Discover’s account may be especially appropriate for people who prefer keeping their emergency savings separate from everyday spending while using an established financial institution.
However, the account’s current availability, APY, transfer arrangements, and applicable terms should be checked before opening it. A competitive account today may become less attractive if its rate falls significantly behind alternatives.
Compare the complete account conditions rather than choosing solely because of the bank’s name or advertised interest rate.
5. Capital One 360 Performance Savings
Capital One 360 Performance Savings is worth evaluating if you want an online savings account with relatively simple requirements. It has generally offered no monthly maintenance fee and no minimum opening deposit.
For people who already use Capital One banking products, keeping savings within the same institution may make account management more convenient. Depending on your existing accounts and transfer arrangements, moving money between accounts may also be easier to organize.
Nevertheless, convenience should not replace a careful review of interest rates and access rules.
An emergency fund needs to remain available when something unexpected happens. Before choosing this account, understand the available transfer methods, processing times, and any applicable transaction restrictions.
Capital One may be a useful choice for someone who values accessible online banking and wants a dedicated savings account without complicated qualification requirements.
Check the current APY before applying and compare it with other eligible accounts offering similar fees and access.
How Much Money Should You Keep in Your Emergency Fund?
A commonly recommended target is three to six months of essential living expenses. Your ideal amount depends on your employment situation, household responsibilities, insurance coverage, and financial commitments.
Someone with a stable job, predictable expenses, and another household income may feel comfortable starting with a smaller reserve. A freelancer, self-employed professional, homeowner, or single-income household may benefit from a larger financial cushion.
Calculate your essential monthly expenses first. Include housing, groceries, utilities, transportation, insurance, minimum debt payments, and necessary healthcare costs.
If these expenses total $3,000 per month, a three-month emergency fund would equal $9,000, while six months would equal $18,000.
You do not need to reach the entire target immediately. Start with a manageable milestone, then gradually increase your savings until you reach an amount that fits your circumstances.
Should You Keep Emergency Savings in One Account or Several?
Both approaches can work, depending on your needs.
Keeping your entire reserve in one high-yield savings account can make tracking your money easier. You have one balance to monitor, one interest rate to review, and fewer accounts to manage.
Alternatively, you can divide your emergency money between a readily accessible checking account and a separate high-yield savings account.
For example, someone with a $12,000 emergency fund might keep $2,000 in checking for immediate expenses and place the remaining $10,000 in savings.
This arrangement can provide quick access to a smaller amount while allowing the majority of the reserve to earn interest.
If you use multiple banks, test the transfer process before an emergency occurs. Also remember that deposit insurance limits apply according to the legal bank, depositor, and ownership category, not simply the number of accounts you open.
Are Certificates of Deposit Suitable for Emergency Savings?
Certificates of deposit (CDs) can offer attractive interest rates, but they are not always the best place for money you may need unexpectedly.
Traditional CDs generally require you to leave your money deposited for a specified term. Withdrawing early may result in a penalty, which can reduce the interest you earn.
No-penalty CDs may provide more flexibility, depending on their specific conditions. However, you should understand the withdrawal rules and any waiting periods before using one for emergency savings.
For most households, the main emergency reserve should remain in an account that allows convenient access without an early-withdrawal penalty.
A CD may be worth considering for additional savings beyond your immediate emergency requirements, provided you can accept its limitations.
How to Build Your Emergency Fund Consistently
Building an emergency fund becomes easier when saving is part of your regular financial routine.
Automate your contributions. Schedule a transfer from checking to savings shortly after payday. Even a modest contribution can grow when repeated consistently.
Set realistic milestones. Work toward your first $500 or $1,000 before moving on to one month of essential expenses and eventually your full target.
Reduce avoidable spending. Review subscriptions, dining expenses, and other flexible costs to identify money you can redirect toward savings.
Save unexpected income. Tax refunds, work bonuses, gifts, or additional earnings can help you reach your target faster.
Review your progress regularly. Recalculate your target whenever your housing costs, family responsibilities, insurance expenses, or income change.
Consistency is usually more important than making large deposits occasionally. A sustainable savings habit can help you build financial security without placing excessive pressure on your monthly budget.
Frequently Asked Questions
1. What is the best account for an emergency fund?
For most people, an FDIC-insured high-yield savings account is a practical choice because it combines deposit protection, interest earnings, and access to cash.
2. Can I use a regular bank savings account?
Yes. A regular savings account can work if it provides suitable access and deposit protection. However, compare its APY with competitive alternatives to avoid unnecessarily low interest earnings.
3. Is an online savings account safe?
Eligible deposits at FDIC-insured banks receive federal deposit-insurance protection within applicable limits. Verify that the institution holding your money is actually FDIC-insured.
4. Should I choose the account with the highest APY?
Not automatically. Consider fees, withdrawal options, minimum balances, linked-account requirements, and transfer speed alongside the advertised rate.
5. How often should I review my savings account?
Review your account every few months and whenever your bank changes its terms. Consider switching if another suitable account offers a meaningfully better long-term combination of interest, access, and simplicity.
6. Should I invest my emergency fund in stocks?
Generally, your core emergency reserve should not depend on investments that can lose value. Savings accounts are more suitable for money you may need during an unexpected financial setback.
7. Can I keep my emergency fund at the same bank as my checking account?
Yes. Using the same bank may simplify transfers, while a separate institution can help reduce unnecessary spending. Choose the arrangement that balances accessibility and financial discipline.
8. When should I use my emergency fund?
Use it for necessary, unexpected expenses such as urgent medical bills, essential repairs, or temporary income loss. Predictable expenses and planned purchases are better handled through separate savings categories.
Conclusion
Choosing the right emergency fund account means comparing interest rates, fees, deposit protection, and accessibility. Marcus, Ally, EverBank, Discover, and Capital One are worth considering based on their current rates and terms. Set a realistic savings goal, automate contributions, and review your progress regularly. Keeping emergency savings safe, accessible, and separate from everyday spending can help you manage unexpected expenses with greater confidence.
Related Reading

[…] Best Savings Accounts for Building a Reliable Emergency Fund […]